

Stay in the know
Receive timely insights and briefings from HSF Kramer, tailored to keep you informed and ahead
Subscribe now
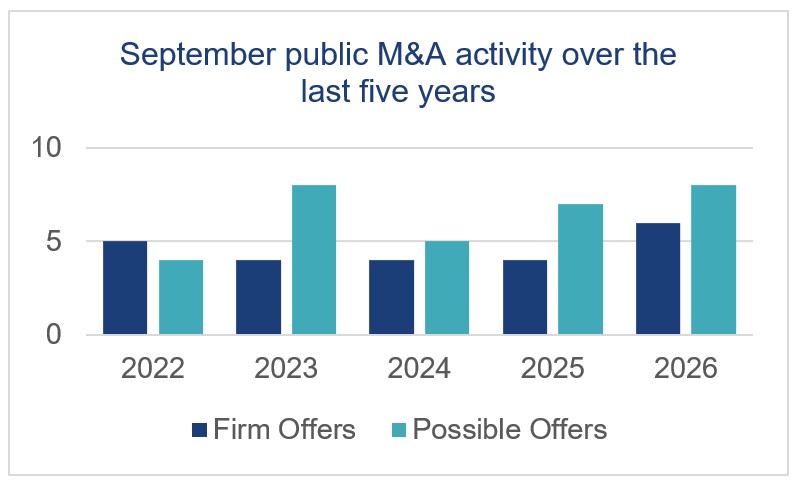
In September 2026, there were six Rule 2.7 announcements made across the UK public M&A market and eight further possible offers announced.


In the UK, hostile takeovers are unusual. Bidders place value on securing the target board’s recommendation of an offer before taking it to shareholders and are typically reluctant to voluntarily start a 28-day ‘put up or shut up’ period.
However, in recent months we have seen a number of bidders use a bear hug – where the bidder seeks to appeal directly to target shareholders if the target board is refusing to engage.
Deals where we have seen this tactic used this year include the possible offers by Prologis for SEGRO, Helios for CAB Payments, Railpen for IP Group and Castlelake for easyJet. In each case, they used their possible offer announcements to appeal to target shareholders and ask them to encourage the target board to engage with the bidder’s proposal.
A bear hug can be used either to make a possible offer public for the first time or, where there has already been a leak, to voluntarily update the market about improved proposals submitted since that leak (see, for example, EQT’s possible offer for Intertek and Castlelake’s possible offer for easyJet).
For more information on bear hugs, see our article here.
The Takeover Panel published a statement (Panel Statement 2026/12) in relation to a breach of Rule 4.2(a) of the Takeover Code on the £1.4 billion bid for Spire Health Group by a consortium including Toscafund and Ares Management.
Rule 4.2 of the Takeover Code states that during an offer period “neither an offeror nor any person acting in concert with it may sell any securities in the offeree company” except with the prior consent of the Panel and following 24 hours public notice that such sales might be made.
Following the Rule 2.7 announcement, Bridgemere Securities Limited – a person acting in concert with Bidco – sold shares it held in Spire representing approximately 5.57% of the target’s shares.
The consent of the Panel was not obtained prior to the sale of Spire shares nor was the requisite public notice given.
The Panel Executive has imposed the same restrictions that would have applied had the sale of Spire’s shares by Bridgemere Securities been properly authorised under Rule 4.2. Accordingly:
Both Spire and Bidco accepted the ruling.
In this episode of our public M&A podcast series, we talk about the UK Takeover Panel’s latest consultation paper (PCP 2026/1) which seeks views on a series of miscellaneous changes to the Takeover Code. Proposals being consulted on include:
To listen to the full conversation please visit SoundCloud, Spotify or Apple. We also discuss the consultation paper in our blog post here.
September has seen activity fairly consistent with the same period across the last five years. Firm offers saw an uptick from 2025, with six announced this month compared to four in 2025, while possible offers rose from seven to eight over the same period. In terms of sectors, September was an active month for the technology sector with two firm offers and one possible offer announced.
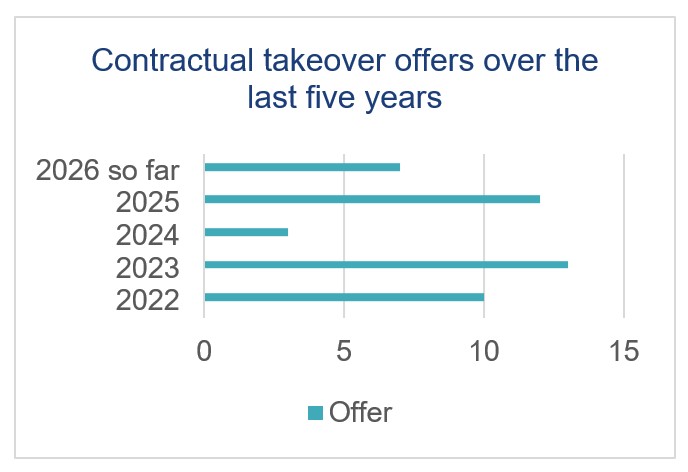
As seen in previous years, the scheme of arrangement remains the acquisition structure of choice. September saw all six firm offers being by way of scheme of arrangement, including Veritas Capital Fund Management, L.L.C.’s offer for Bodycote plc valued at £1.64 billion and Epiris LLP’s offer for Gamma Communications plc valued at £1.015 billion. However, in recent months we have seen more contractual takeover offers, with seven of the firm offers announced in 2026 so far being by way of contractual takeover offer. This is reflective of the fact we have seen more hostile offers and competitive situations.

Partner, Head of M&A, London

Partner, London

Partner, London

Knowledge Counsel, London

Partner, London

Partner, London

Partner, London

Partner, London
The contents of this publication are for reference purposes only and may not be current as at the date of accessing this publication. They do not constitute legal advice and should not be relied upon as such. Specific legal advice about your specific circumstances should always be sought separately before taking any action based on this publication.
© Herbert Smith Freehills Kramer 2026
Receive timely insights and briefings from HSF Kramer, tailored to keep you informed and ahead